Traditional banking models ignore the exact people who drive local economies forward. Mainstream financial institutions often demand collateral, credit scores, and years of audited profit margins that grassroots entrepreneurs simply do not have. That barrier locks millions of ambitious founders out of the financial system.
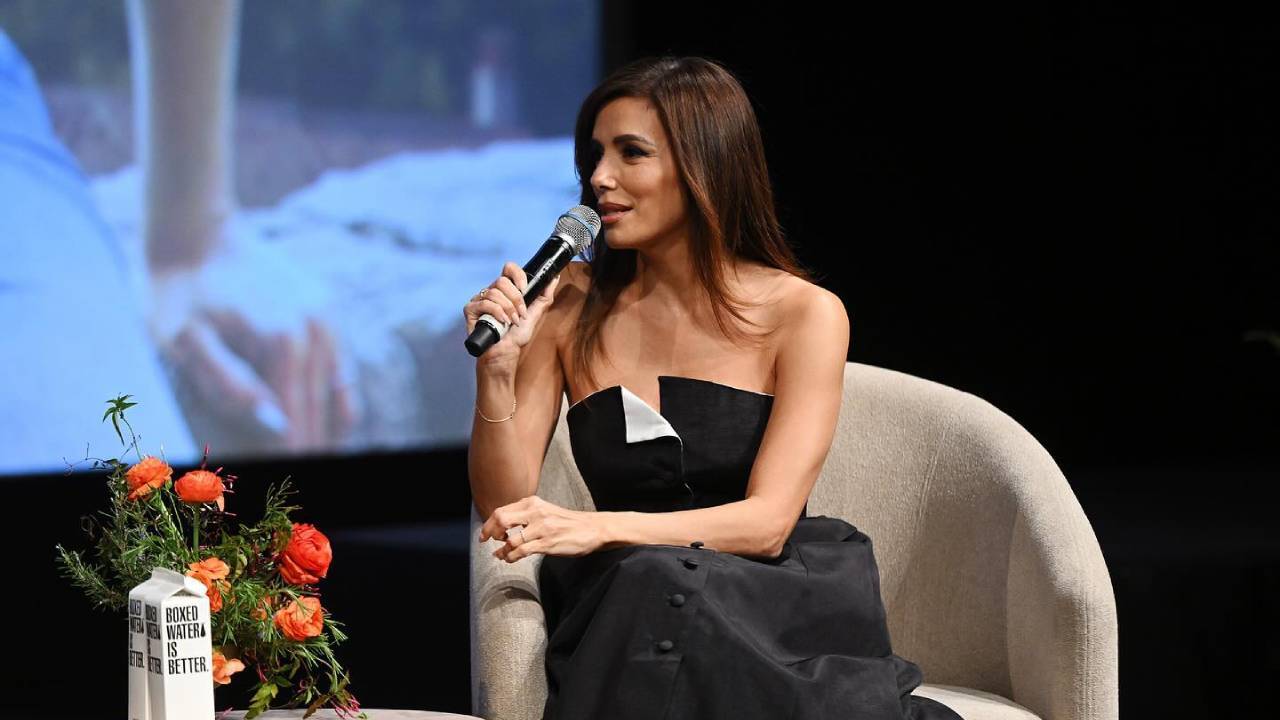
Back in 2013, a small partnership launched with modest ambition and a clear target. The Eva Longoria Foundation joined forces with Accessity, a California-based nonprofit lender, to set up a $55,000 fund aimed at six women. It looked like a drop in the ocean compared to Wall Street venture capital rounds. If you found value in this post, you might want to look at: this related article.
Yet, looking at the numbers a decade later tells a completely different story. That initial capital pool generated nearly $525,000 in microloans. More importantly, it helped create or maintain 150 jobs in local communities.
Why Microloans Succeed Where Banks Fail
Commercial banks evaluate risk through rigid algorithms. They look at a spreadsheet and decide whether a neighborhood bakery or a mobile food vendor fits their risk threshold. Most of the time, they do not. For another angle on this development, see the recent update from MarketWatch.
Microloan programs change the evaluation metric. They look at community impact, business viability, and personal grit. When founders receive access to early-stage capital, they bypass predatory lenders charging triple-digit interest rates.
Take the expansion funded by these initiatives. The model relies on recycling repaid capital back into the community. As the initial six recipients paid back their loans, those funds rolled over into new loans for other business owners. Over the years, the program scaled to support dozens of successful business cycles without requiring infinite cash injections.
Education Beats Cash Alone
Throwing money at a problem rarely fixes structural disadvantages. Capital without financial literacy often leads to business failure within the first two years.
Successful micro-lending initiatives pair every dollar with rigorous education. Programs run alongside lenders like Accessity offer Spanish-language entrepreneurial training, digital marketing workshops, and direct mentorship.
Participants learn how to manage cash flow, separate personal finances from business revenue, and navigate local zoning laws. Founders do not just get a check. They get a playbook for survival.
When Latina entrepreneurs gain access to both capital and institutional training, failure rates drop sharply. Many recipients scale from a single home-based operation into multi-unit businesses employing local workers.
The Broader Impact on Local Economies
Small businesses form the backbone of neighborhood commerce. When a Latina-owned business secures a microloan, the economic ripple effect stays local. Founders hire neighbors, buy supplies from nearby vendors, and reinvest profits back into the immediate community.
Data from the long-term partnership shows that small injections of capital spark exponential community growth. A $5,000 or $10,000 microloan can purchase essential equipment, secure a commercial kitchen lease, or fund inventory for peak season.
Traditional finance fails to capture this velocity. Wall Street looks for unicorn startups seeking billions, while Main Street thrives on small, disciplined investments that generate steady, dependable cash flow.
If you want to support grassroots economic growth, stop waiting for corporate philanthropy to fix systemic gaps. Support regional community development financial institutions, buy from local micro-entrepreneurs, and back initiatives that prioritize access over bureaucracy.